
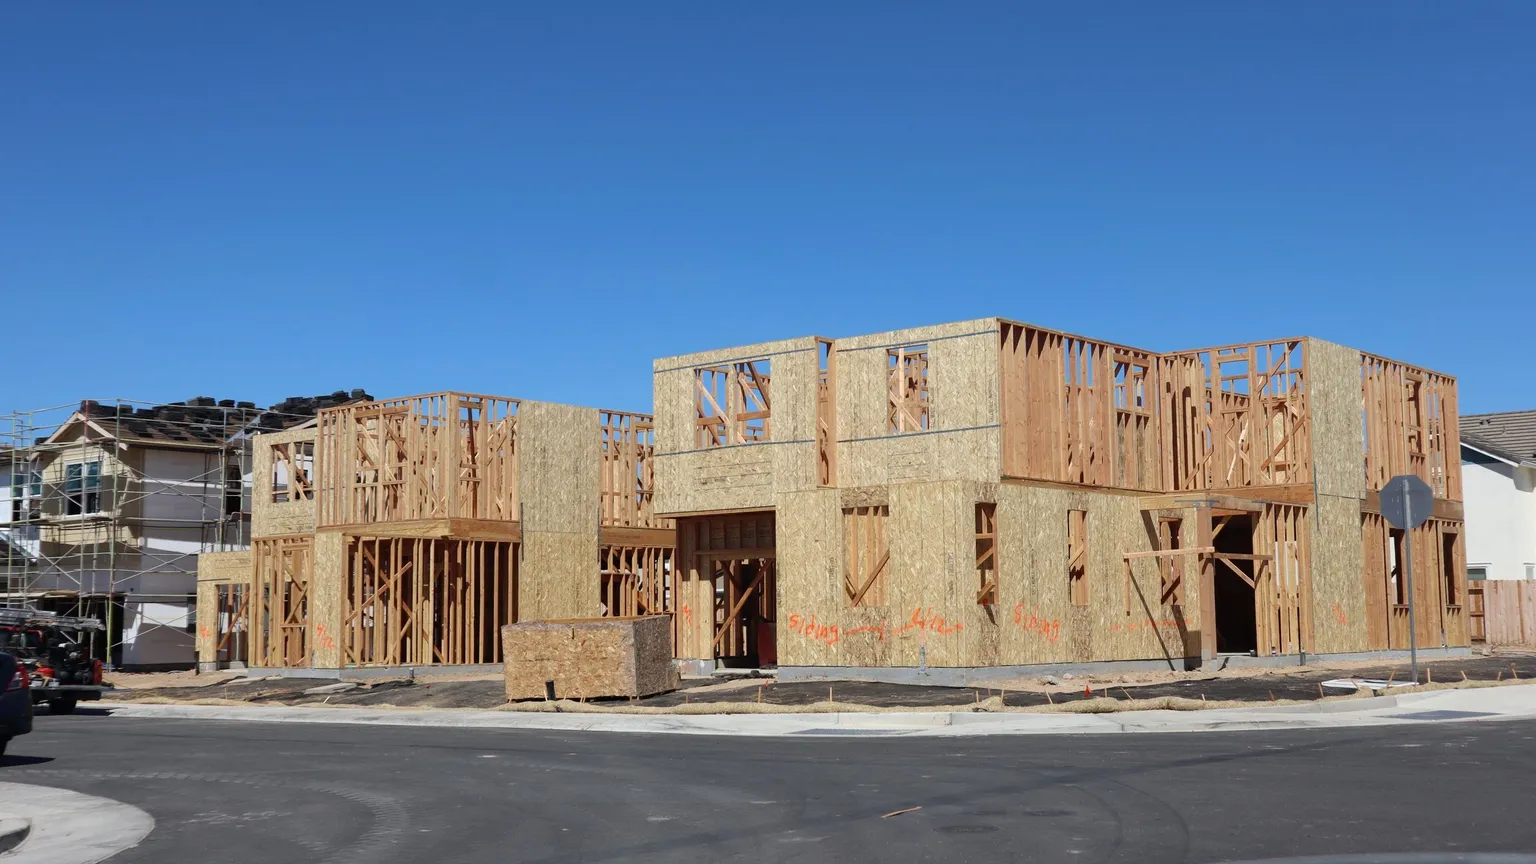
You have sold the last lot of a small subdivision, or you have just exchanged on your first completed duplex, and you are working out what actually lands in the bank. Then the settlement statement arrives and the amount is lower than the contract price. Nothing has gone wrong, necessarily. Part of the price may have gone to the Australian Taxation Office instead of to you.
This is a cash-flow issue before it is a tax issue, and on a thin-margin project it is worth understanding before you sign anything.
The deal question: whose money is it at settlement?
Where GST at settlement applies, the buyer does not pay the whole price to the seller. The buyer withholds an amount and remits it to the ATO, and the seller then credits that amount against its own GST liability. The ATO's GST at settlement guidance describes the mechanism and the transactions it covers, which include new residential premises such as house and land packages, off-the-plan sales, display homes and new apartments, as well as potential residential land.
For a subdivision, the practical question is simple and slightly uncomfortable: are the lots I am creating new residential premises or potential residential land? If the answer is yes, the withholding machinery may apply, and the way you price, contract and settle the project changes.
How the amounts work
The withholding is calculated on the price, and the ATO's own examples show how it operates. In one example on the GST at settlement page, the supplier's notification states a withholding obligation of $81,818, described there as one eleventh of a $900,000 price. In another example, where the property is sold under the margin scheme, the buyer withholds and pays 7 per cent of the contract price, and the seller reports the sale on its activity statement and receives the difference as a refund.
Two things follow from those examples. First, the withholding is not a tax on the buyer; it is the seller's GST, collected early. Second, the margin scheme materially changes the amount withheld, which is why eligibility matters so much on developments.
Margin scheme eligibility: the question people get wrong
The margin scheme can reduce the GST payable, but it is not a box you tick for convenience. The ATO's eligibility guidance makes two things clear. The parties must have a written agreement to use the margin scheme before settlement. And there are acquisitions that make the scheme unavailable, including property purchased as a fully taxable sale where the margin scheme was not used, and, for sales on or after 9 December 2008, property purchased as part of a going concern, as GST-free farmland, or from an associate for no payment where the seller was not eligible.
The chain matters. As the ATO puts it, if the previous owner of the property was not eligible to use the margin scheme, you generally will not be able to use it. That is a title-history question, and it is one to resolve before you buy, because you inherit the answer.
The method of calculating the margin then depends on when the property was acquired: the consideration method is required for property purchased after 1 July 2000, and the valuation method is available only for property held before that date and only with an approved valuation. Which method applies, and whether a valuation is needed, is not something to work out at settlement.
The checks a capable student would run, in order
- Decide the character of the supply at feasibility stage. Ask your accountant whether what you are creating is new residential premises or potential residential land, and write the answer down with the date and the basis.
- Check the acquisition history of the land. Ask how the vendor acquired it and whether the margin scheme was available to them. If they cannot show it, you may not have it either.
- Put the agreement in the contract. Because the written agreement must be in place before settlement, the margin scheme cannot be bolted on later. Have your lawyer include it properly, or advise deliberately that it does not apply.
- Model the cash at settlement. Build the withholding into the settlement cash flow so the number you are expecting is the number you receive, and make sure the development loan and the profit distribution forecast reflect it.
- Check the notifications. The ATO's guidance states that the seller must notify the purchaser in writing and state the withholding amount, and that this can sit in the sales contract or in a separate document before settlement. Your conveyancer should know exactly which document carries it in your transaction.
The trap: pricing the project as though the whole price is yours
The common mistake is a feasibility that treats the contract price as the cash received. It overstates the cash available at settlement and can understate the peak debt position if interest is still running.
The second mistake is assuming the margin scheme automatically improves the position. It changes the calculation and the withholding, but it is unavailable in the circumstances the ATO describes, and a written agreement that is missing or wrong at settlement is a problem you cannot fix after the fact.
Timing and the rest of the tax picture
The withholding is a Commonwealth GST mechanism, and it sits alongside - not instead of - state and territory duty and land tax, and alongside the income tax and capital gains treatment of the project. A subdivision that looks straightforward can carry several different tax consequences, each with its own timing. That is why the tax advice has to happen when the deal is being structured, not when the lots are being sold.
The Think Property Club lesson
Feasibility is not just construction cost and end value. It is the cash that actually moves, on the dates it actually moves. GST at settlement is one of the clearest examples: a Commonwealth rule, triggered by what you created, that changes the settlement funds and therefore the finance requirement.
You are not expected to resolve this yourself. Recognise the trigger, gather the facts about how the land was acquired, and brief an accountant or tax adviser who works with property development, together with a property lawyer who will get the notifications and the margin scheme agreement into the contract properly.
Your next actions before you contract
- Get written advice on whether the completed supply is new residential premises or potential residential land, and keep it with the file.
- Ask the vendor, in writing, how the land was acquired and whether the margin scheme was available to them.
- Confirm how the ATO notification and any margin scheme agreement will be documented, and by whom, before settlement.
- Rerun the settlement cash flow with the withholding included, and check it against your peak debt limit.
- Confirm with your broker or lender that the facility accommodates the reduced settlement proceeds.
Sources and boundaries
Sources checked 29 September 2026. Jurisdiction and limits: Australia-wide information about Commonwealth GST law. The withholding rules discussed here apply to certain taxable supplies of new residential premises and potential residential land, and the detail is set out in the ATO's GST at settlement guidance and the related legislation and rulings. The margin scheme rules depend on when and how the property was acquired and on the eligibility of the entity that sold it, and the ATO publishes the current tests and methods. Neither is a substitute for state or territory duty, land tax or other charges, and none of the figures quoted in the ATO examples in this article should be applied to a particular property. Tax law changes, and every conclusion depends on the individual transaction.
- ATO — GST at settlement. Used for: When withholding applies, what the supplier must notify, and the ATO worked examples (Checked 29 September 2026)
- ATO — Eligibility to use the margin scheme. Used for: Written agreement requirement and the circumstances where the margin scheme cannot be used (Checked 29 September 2026)
- ATO — Calculating the GST payable under the margin scheme. Used for: One eleventh of the margin; consideration and valuation methods (Checked 29 September 2026)
This article is general education, not personalised planning, legal, financial, tax, privacy, safety or building advice. Requirements and outcomes vary by jurisdiction, site, contract, structure and circumstances. Check current information with the relevant authority and appropriately qualified advisers.
 Learn with Jason & AmyBuild practical small-scale property development skills with experienced mentors.Enquire now
Rate this article
Guest rating: select 1 star for poor or 5 stars for great. No account is required.
Leave a comment
Join the discussion. Your email address will not be published.
Frequently asked questions
What is GST at settlement?
It is a withholding mechanism. For certain taxable supplies of new residential premises or potential residential land, the buyer withholds an amount from the contract price at settlement and pays it to the ATO rather than paying the full price to the seller. The seller then credits that amount against its GST liability.
How much is withheld?
The ATO sets out the amounts on its GST at settlement page: in its examples, one eleventh of the price where the margin scheme does not apply, and 7 per cent of the contract price where the property is sold under the margin scheme. Use the ATO's tools and your own adviser rather than a rule of thumb.
Who tells the buyer what to withhold?
The supplier does. The ATO states that a seller of residential premises or potential residential land must notify the purchaser in writing and state the withholding amount, and that the notification can be included in the sales contract or in a separate document before settlement.
Does the margin scheme reduce what the buyer withholds?
It changes it, which is why eligibility matters. Where the margin scheme applies, one eleventh of the margin is the GST, and the ATO's settlement example withholds 7 per cent of the contract price instead of one eleventh. Eligibility is not automatic: the ATO requires a written agreement to use the margin scheme before settlement, and there are acquisitions that make the scheme unavailable.
Can I fix this after contracts are signed?
It is far better to get it right before. The notification, the margin scheme agreement and the treatment of the withholding all have to be reflected in the contract documentation and in the settlement statement. Reworking them late creates cost, delay and a real risk of getting the GST treatment wrong.
Photo: Pexels, free to use under the Pexels licence.
Loading comments…